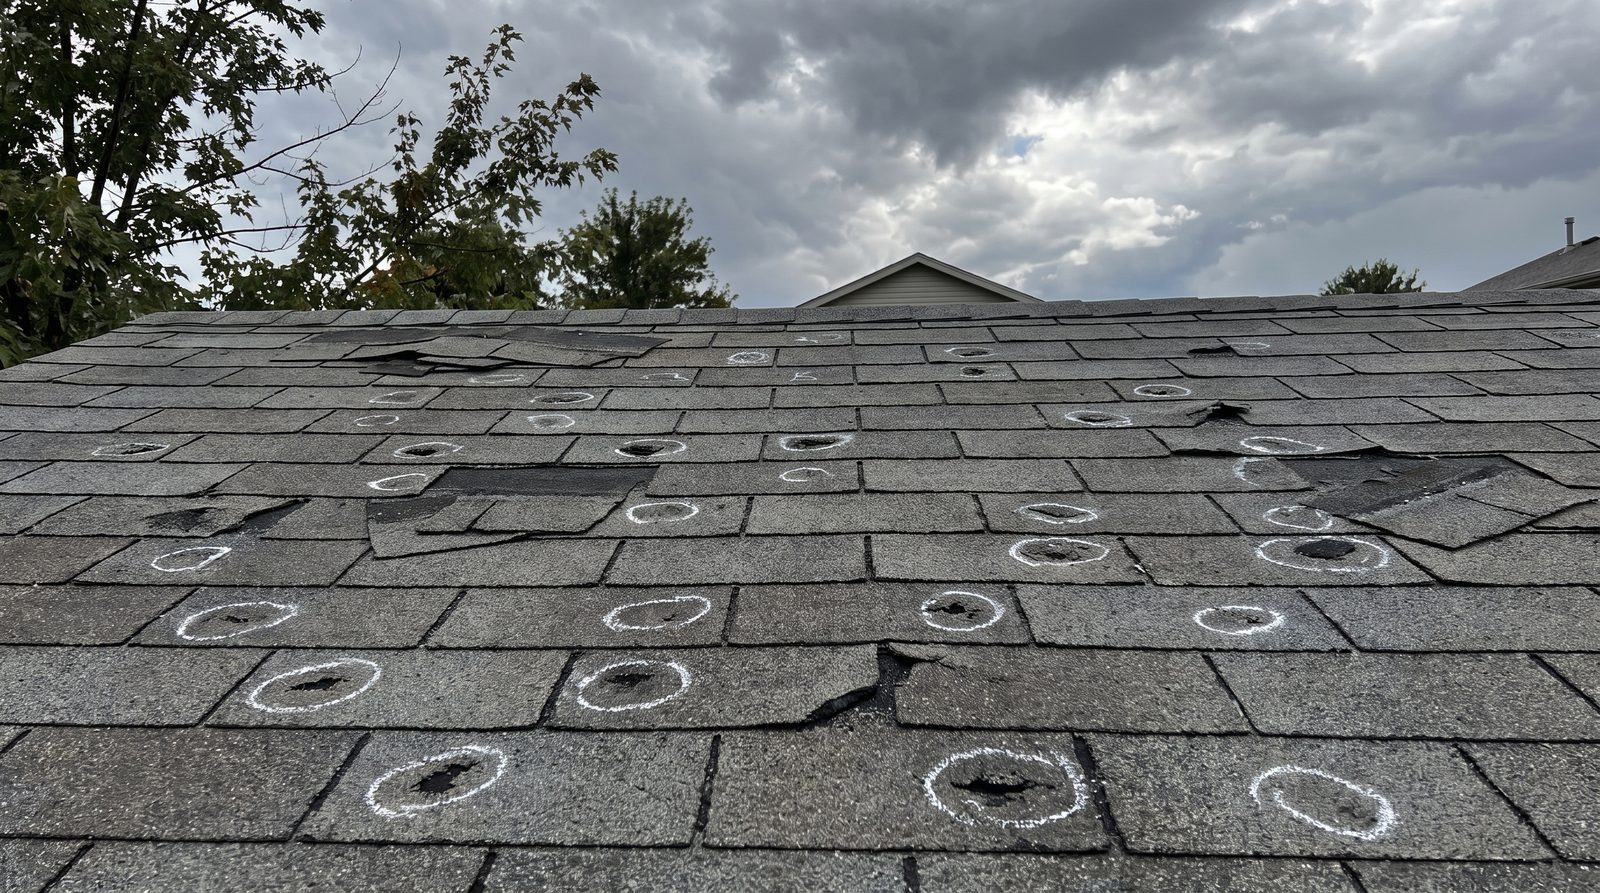
Storm and wind damage
We document the damage, meet your adjuster on the roof, and handle the parts of a claim most homeowners do not know to ask about.
Report storm damageEmergency tarpWhat hail and wind damage actually look like
Most storm damage is invisible from the ground. That is the whole problem: your roof can be totalled and look fine from the driveway.
Hail
- Round bruises where granules are knocked off and the mat is soft
- Dents in the gutters, downspouts, vents and flashing
- Dings in the AC condenser fins and on the mailbox
- Granules piled at the bottom of the downspout
- Splatter marks on the deck, fence or window sills
Wind
- Shingles lifted, creased or missing entirely
- A whole slope that looks ruffled after the storm
- Ridge cap displaced or gone
- Debris impact marks and tree strikes
- Exposed nail heads where the seal broke
Time matters. Most carriers put a deadline on filing after the date of loss. If a storm went through, get it looked at even if nothing is leaking yet.
How an insurance claim actually goes
What we hand your adjuster
A claim is won or lost on documentation. Here is what goes in the file.
- Date of loss and the weather event it maps to
- Photographed test squares on every slope
- Close-ups of every hail hit and wind crease, marked and counted
- Collateral damage: gutters, vents, flashing, screens, AC fins
- Interior photos of any water intrusion
- Roof measurements and a diagram with squares by slope
- Line-item scope of what a correct repair requires
- Code-required items your carrier owes but the field scope often omits
How to spot a storm chaser
After a hailstorm, out-of-state crews arrive within days, sign as many roofs as they can, and are gone before the first warranty call. Ask any contractor who knocks on your door these questions.
| Ask them | What a local contractor answers |
|---|---|
| Where is your office? | An address in this county you can drive to. |
| What is your Tennessee licence number? | Given without hesitation, and it checks out online. |
| Are you BBB accredited? | Yes, with a rating you can look up right now. |
| Are you manufacturer certified? | Yes, and that is why the manufacturer warranty can be registered. |
| Who honours the workmanship warranty in three years? | The same company, still at the same address. |
| Will you cover my deductible? | No. That is not legal, and anyone offering it is telling you how they do business. |
On deductibles. A contractor cannot pay, waive, rebate or absorb your insurance deductible. If someone offers to “eat the deductible” or write it off as a discount, that is insurance fraud and it puts your claim at risk, not just theirs.
Questions we get about claims
Will filing a claim raise my rates?
A weather claim is not the same as an at-fault claim, and carriers treat them differently. We are roofers, not agents, so the honest answer is: ask your agent before you file. We will give you the documentation either way so you can make that call with real information.
What does it cost me?
Your deductible. That is the homeowner's part of an approved claim, and it is the only part we can collect from you on claim work.
The adjuster only approved a repair. Is that final?
Not necessarily. Scopes get revised when documentation shows the repair is not feasible — discontinued shingles, brittleness, or code requirements. That is what a supplement is for.
My claim was denied. What now?
You have the right to cancel a contract tied to that claim within the window Tennessee law provides after you are notified of the denial. We will walk you through re-inspection options, and if the damage is real but the paperwork is thin, that is usually fixable.
How long does the whole thing take?
The carrier sets the pace, not us. Inspection to adjuster meeting is usually one to three weeks. Approval to installation depends on materials and weather.
Do you do the tarp before the claim is settled?
Yes. Preventing further damage is your responsibility under most policies, and the tarp is usually a reimbursable line item. Keep the receipt.
Can you talk to my insurance company for me?
With your written authorization, we can speak with your carrier and meet your adjuster. We do not ask you to sign over your claim benefits, and you should be cautious with any contractor who does.
Report storm damage
The more you can tell us here, the faster the inspection goes. Photos help, but do not get on the roof to take them.
Not sure it is worth filing?
That is exactly what a free inspection is for. We will tell you if the damage will not beat your deductible, and you will have the report either way.
Report storm damageJust book an inspection